◆ Independent analysis · Not for redistribution ◆
Free accessEvery analysis is free in full to registered accounts.Create a free account →
dd
▸Gulf of Guinea One-pagers

Senegal

Single-sheet assessments: the situation, who decides and the way in, on one page. Built from open sources and free to read.

Country · SNG-CTY-01 · v1.1

Senegal — Country

Power map, pressure points and openings, seven weeks before the dissolution window · status 15 October 2026

Issued 15 October 2026
Next revision 22 October 2026
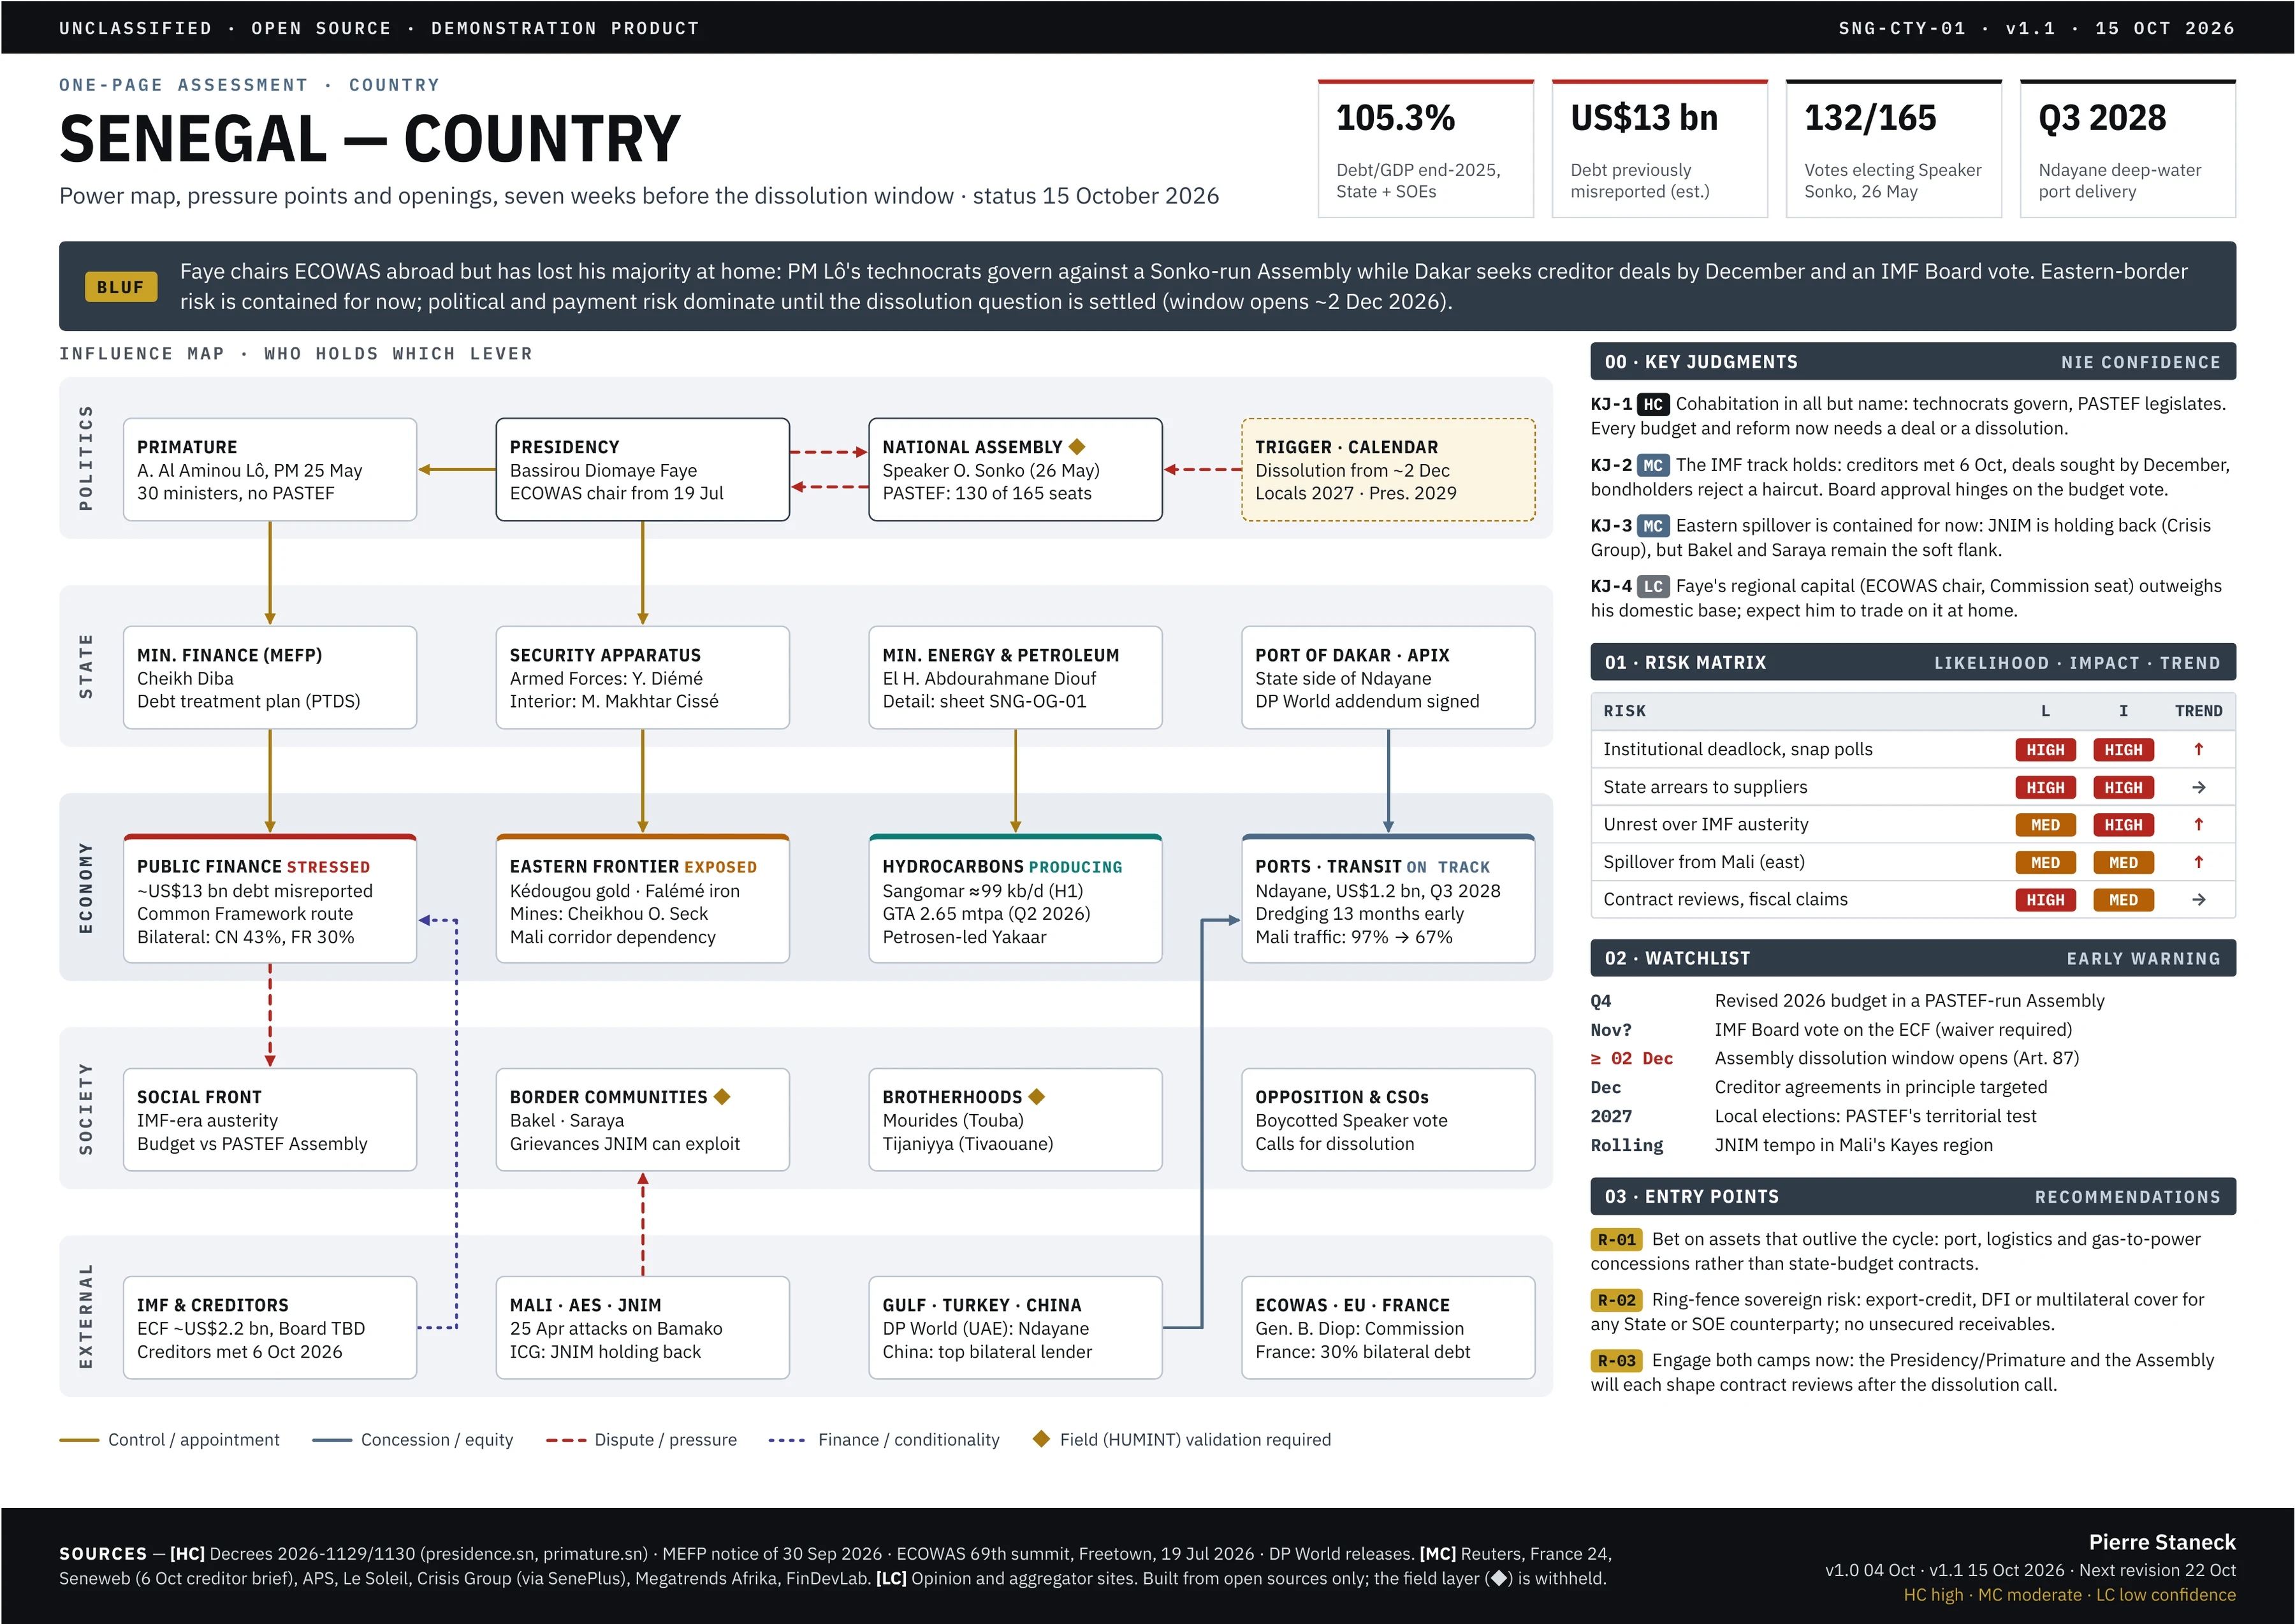
One-page assessment — Senegal — Country
▸ Read the text version

Bottom line

Faye chairs ECOWAS abroad but has lost his majority at home: PM Lô's technocrats govern against a Sonko-run Assembly while Dakar seeks creditor deals by December and an IMF Board vote. Eastern-border risk is contained for now; political and payment risk dominate until the dissolution question is settled (window opens ~2 Dec 2026).

  • 105.3%

    Debt/GDP end-2025, State + SOEs

  • US$13 bn

    Debt previously misreported (est.)

  • 132/165

    Votes electing Speaker Sonko, 26 May

  • Q3 2028

    Ndayane deep-water port delivery

Key judgments

  1. KJ-1 HC Cohabitation in all but name: technocrats govern, PASTEF legislates. Every budget and reform now needs a deal or a dissolution.
  2. KJ-2 MC The IMF track holds: creditors met 6 Oct, deals sought by December, bondholders reject a haircut. Board approval hinges on the budget vote.
  3. KJ-3 MC Eastern spillover is contained for now: JNIM is holding back (Crisis Group), but Bakel and Saraya remain the soft flank.
  4. KJ-4 LC Faye's regional capital (ECOWAS chair, Commission seat) outweighs his domestic base; expect him to trade on it at home.

Risk matrix

Risk Likelihood Impact Trend
Institutional deadlock, snap polls HIGH HIGH ↑
State arrears to suppliers HIGH HIGH →
Unrest over IMF austerity MED HIGH ↑
Spillover from Mali (east) MED MED ↑
Contract reviews, fiscal claims HIGH MED →

Watchlist

Q4
Revised 2026 budget in a PASTEF-run Assembly
Nov?
IMF Board vote on the ECF (waiver required)
≥ 2 Dec
Assembly dissolution window opens (Art. 87)
Dec
Creditor agreements in principle targeted
2027
Local elections: PASTEF's territorial test
Rolling
JNIM tempo in Mali's Kayes region

Entry points

  1. R-01 Bet on assets that outlive the cycle: port, logistics and gas-to-power concessions rather than state-budget contracts.
  2. R-02 Ring-fence sovereign risk: export-credit, DFI or multilateral cover for any State or SOE counterparty; no unsecured receivables.
  3. R-03 Engage both camps now: the Presidency/Primature and the Assembly will each shape contract reviews after the dissolution call.

Sources

[HC] Decrees 2026-1129/1130 (presidence.sn, primature.sn) · MEFP notice of 30 Sep 2026 · ECOWAS 69th summit, Freetown, 19 Jul 2026 · DP World releases. [MC] Reuters, France 24, Seneweb (6 Oct creditor brief), APS, Le Soleil, Crisis Group (via SenePlus), Megatrends Afrika, FinDevLab. [LC] Opinion and aggregator sites. Built from open sources only; the field layer (◆) is withheld.
Sector · SNG-OG-01 · v1.1

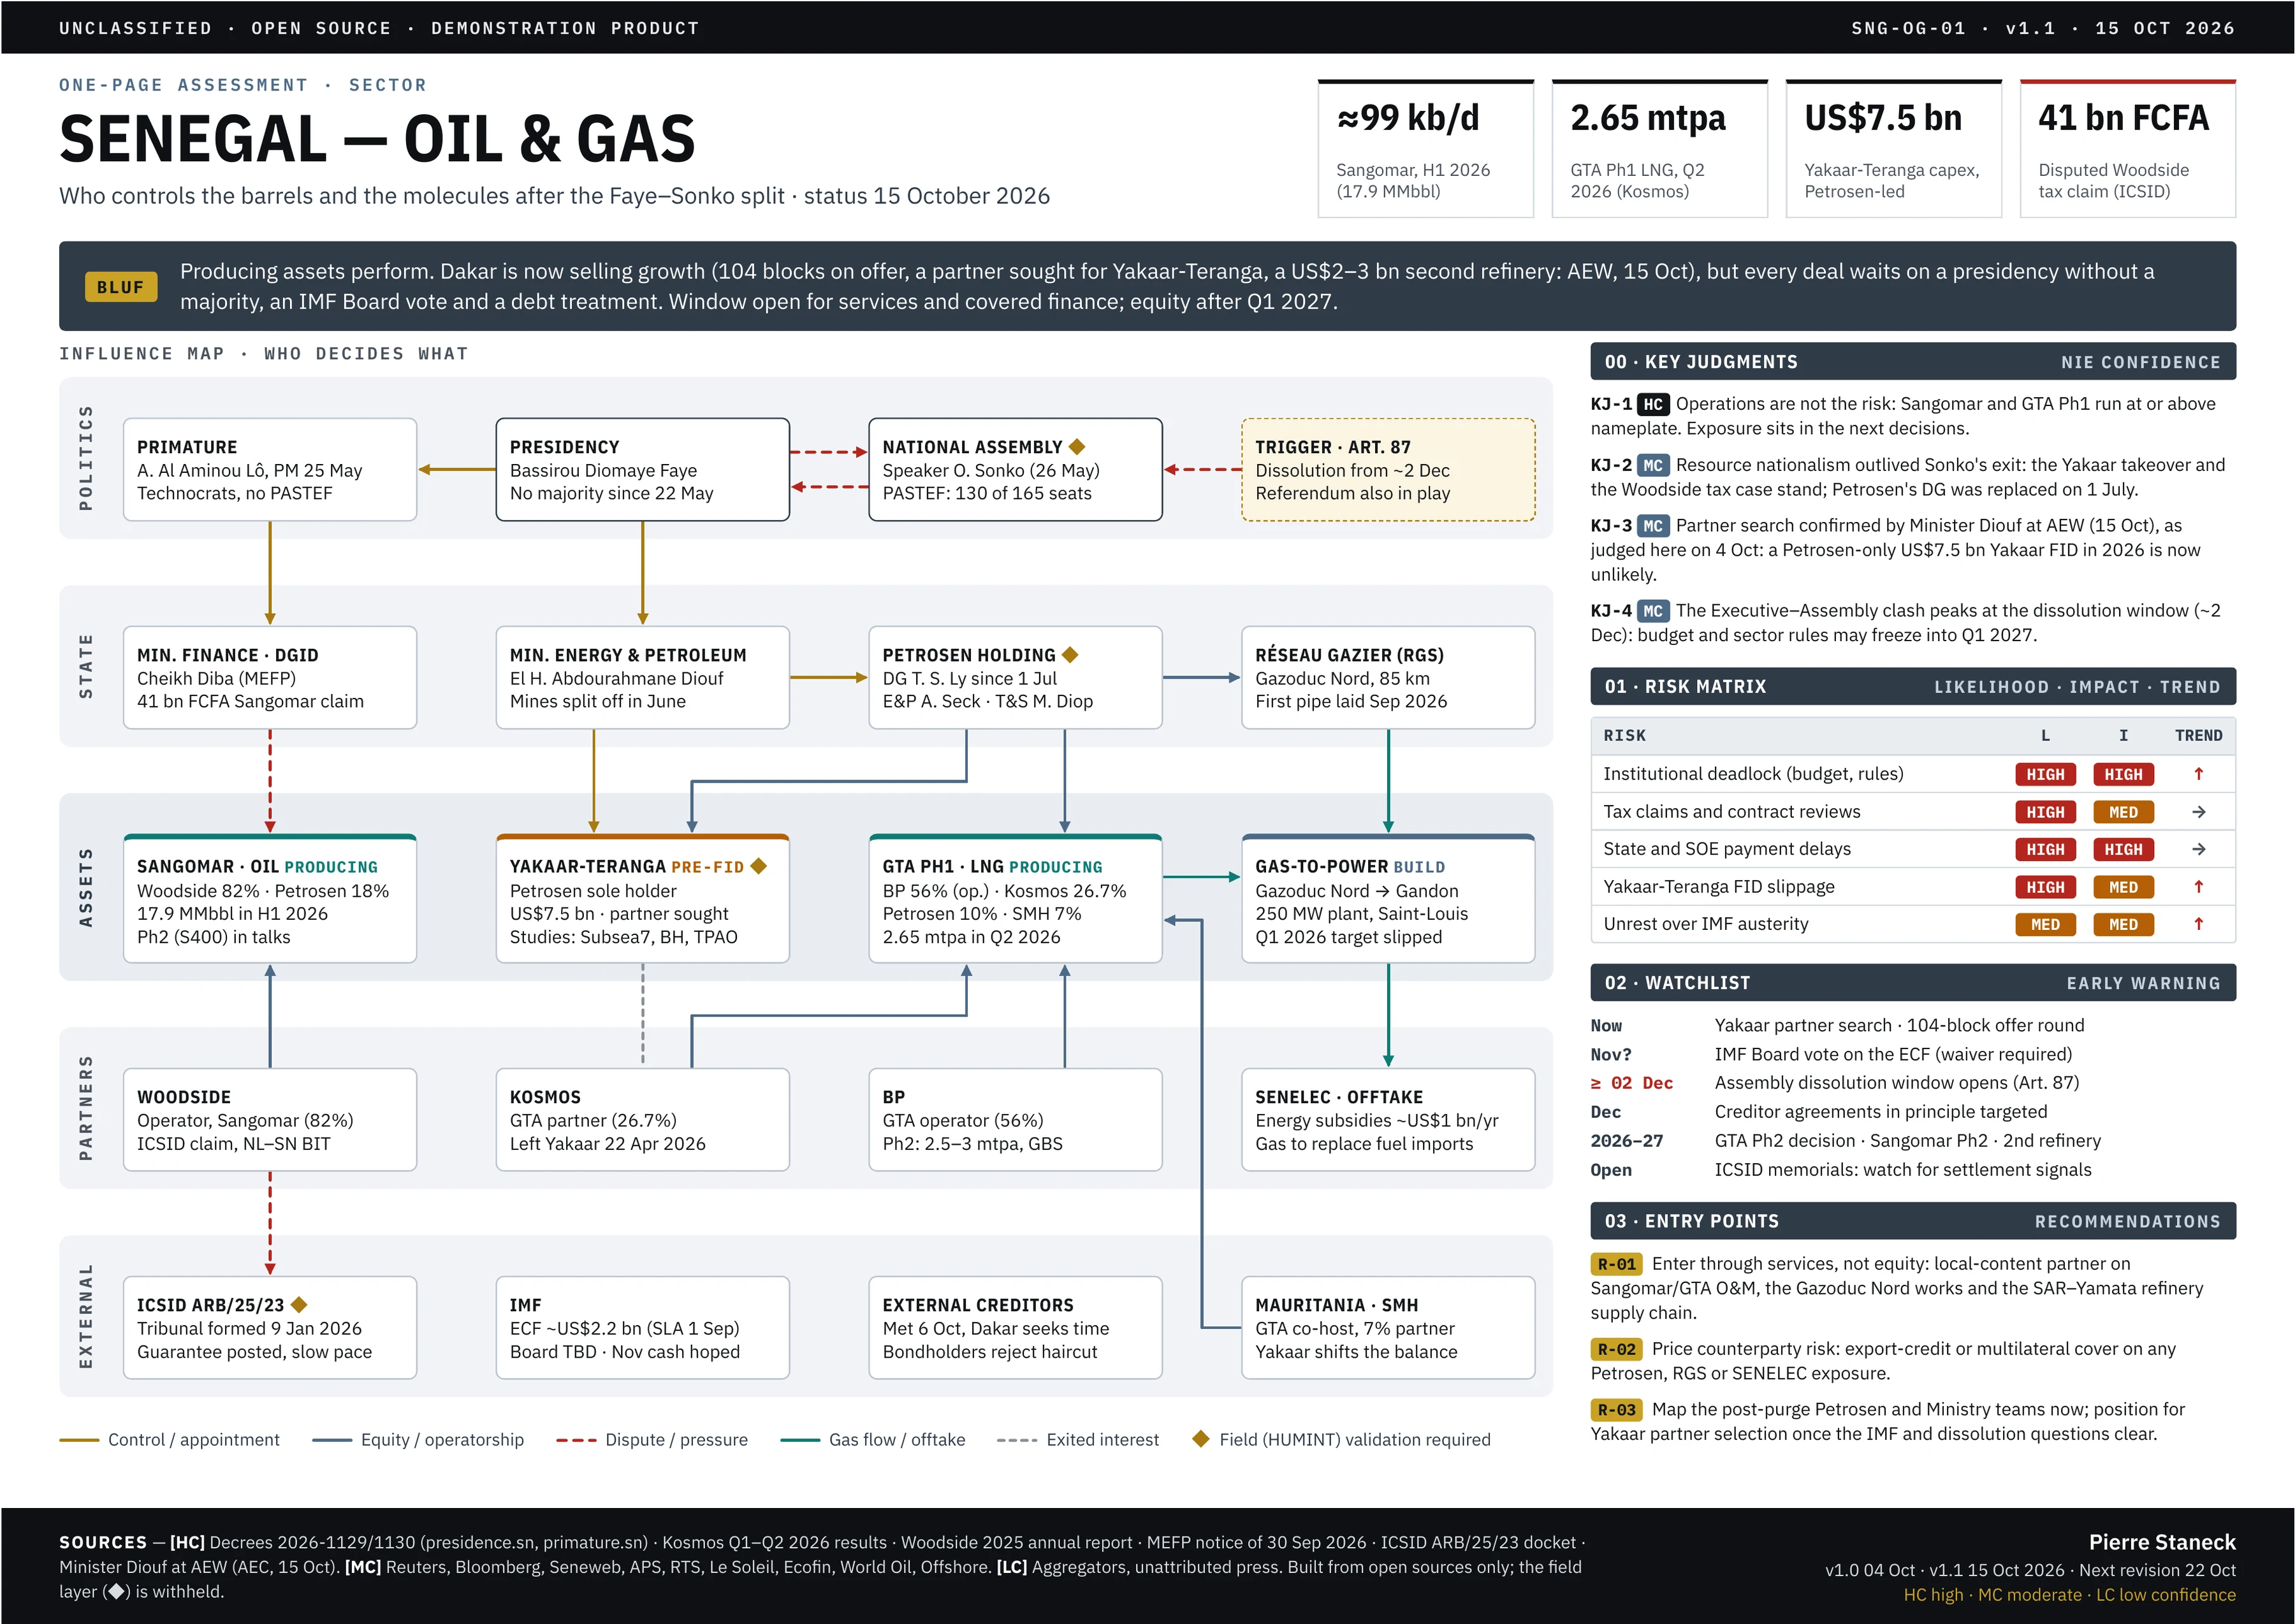
Senegal — Oil & Gas

Who controls the barrels and the molecules after the Faye–Sonko split · status 15 October 2026

Issued 15 October 2026
Next revision 22 October 2026

One-page assessment — Senegal — Oil & Gas
▸ Read the text version

Bottom line

Producing assets perform. Dakar is now selling growth (104 blocks on offer, a partner sought for Yakaar-Teranga, a US$2–3 bn second refinery: AEW, 15 Oct), but every deal waits on a presidency without a majority, an IMF Board vote and a debt treatment. Window open for services and covered finance; equity after Q1 2027.

  • ≈99 kb/d

    Sangomar, H1 2026 (17.9 MMbbl)

  • 2.65 mtpa

    GTA Ph1 LNG, Q2 2026 (Kosmos)

  • US$7.5 bn

    Yakaar-Teranga capex, Petrosen-led

  • 41 bn FCFA

    Disputed Woodside tax claim (ICSID)

Key judgments

  1. KJ-1 HC Operations are not the risk: Sangomar and GTA Ph1 run at or above nameplate. Exposure sits in the next decisions.
  2. KJ-2 MC Resource nationalism outlived Sonko's exit: the Yakaar takeover and the Woodside tax case stand; Petrosen's DG was replaced on 1 July.
  3. KJ-3 MC Partner search confirmed by Minister Diouf at AEW (15 Oct), as judged here on 4 Oct: a Petrosen-only US$7.5 bn Yakaar FID in 2026 is now unlikely.
  4. KJ-4 MC The Executive–Assembly clash peaks at the dissolution window (~2 Dec): budget and sector rules may freeze into Q1 2027.

Risk matrix

Risk Likelihood Impact Trend
Institutional deadlock (budget, rules) HIGH HIGH ↑
Tax claims and contract reviews HIGH MED →
State and SOE payment delays HIGH HIGH →
Yakaar-Teranga FID slippage HIGH MED ↑
Unrest over IMF austerity MED MED ↑

Watchlist

Now
Yakaar partner search · 104-block offer round
Nov?
IMF Board vote on the ECF (waiver required)
≥ 2 Dec
Assembly dissolution window opens (Art. 87)
Dec
Creditor agreements in principle targeted
2026–27
GTA Ph2 decision · Sangomar Ph2 · 2nd refinery
Open
ICSID memorials: watch for settlement signals

Entry points

  1. R-01 Enter through services, not equity: local-content partner on Sangomar/GTA O&M, the Gazoduc Nord works and the SAR–Yamata refinery supply chain.
  2. R-02 Price counterparty risk: export-credit or multilateral cover on any Petrosen, RGS or SENELEC exposure.
  3. R-03 Map the post-purge Petrosen and Ministry teams now; position for Yakaar partner selection once the IMF and dissolution questions clear.

Sources

[HC] Decrees 2026-1129/1130 (presidence.sn, primature.sn) · Kosmos Q1–Q2 2026 results · Woodside 2025 annual report · MEFP notice of 30 Sep 2026 · ICSID ARB/25/23 docket · Minister Diouf at AEW (AEC, 15 Oct). [MC] Reuters, Bloomberg, Seneweb, APS, RTS, Le Soleil, Ecofin, World Oil, Offshore. [LC] Aggregators, unattributed press. Built from open sources only; the field layer (◆) is withheld.

Nexus map · SNG-NET-01 · v1.0

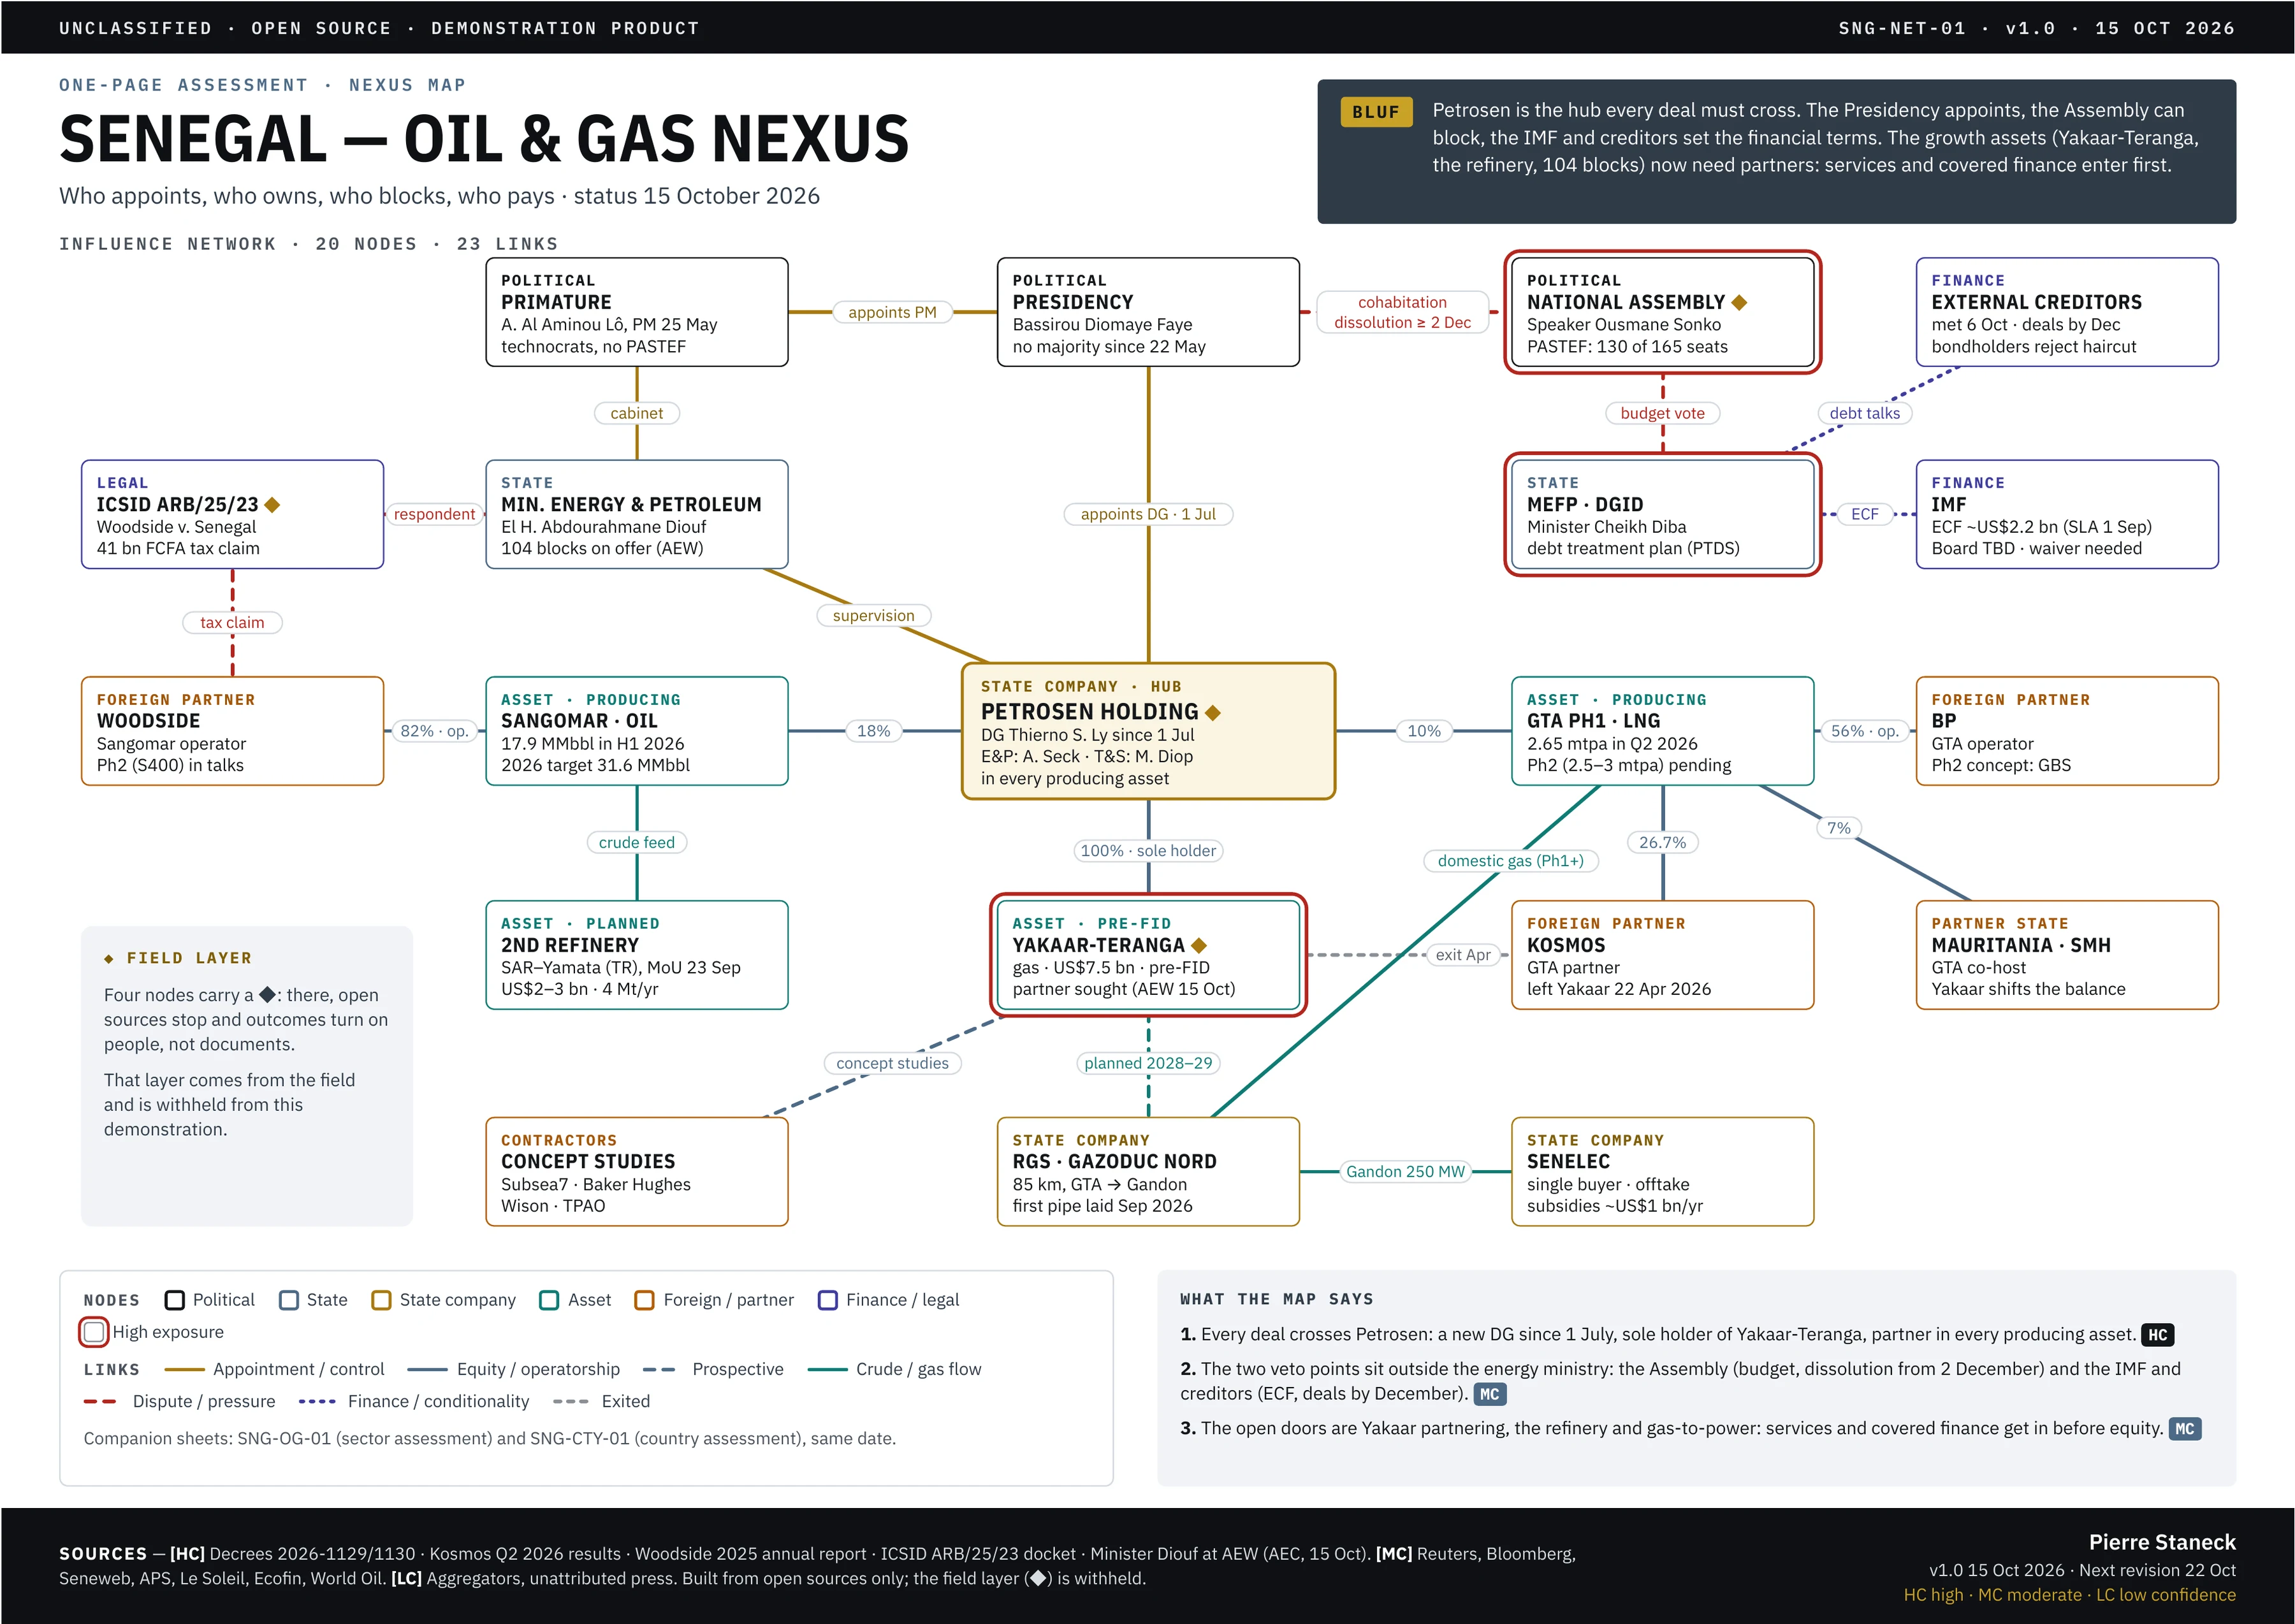
Senegal — Oil & Gas Nexus

Who appoints, who owns, who blocks, who pays · influence network of 20 nodes and 23 links · status 15 October 2026

Issued 15 October 2026
Next revision 22 October 2026

One-page assessment — Senegal — Oil & Gas Nexus
▸ Read the text version

Bottom line

Petrosen is the hub every deal must cross. The Presidency appoints, the Assembly can block, the IMF and creditors set the financial terms. The growth assets (Yakaar-Teranga, the refinery, 104 blocks) now need partners: services and covered finance enter first.

What the map says

  1. 1. HC Every deal crosses Petrosen: a new DG since 1 July, sole holder of Yakaar-Teranga, partner in every producing asset.
  2. 2. MC The two veto points sit outside the energy ministry: the Assembly (budget, dissolution from 2 December) and the IMF and creditors (ECF, deals by December).
  3. 3. MC The open doors are Yakaar partnering, the refinery and gas-to-power: services and covered finance get in before equity.

Sources

[HC] Decrees 2026-1129/1130 · Kosmos Q2 2026 results · Woodside 2025 annual report · ICSID ARB/25/23 docket · Minister Diouf at AEW (AEC, 15 Oct). [MC] Reuters, Bloomberg, Seneweb, APS, Le Soleil, Ecofin, World Oil. [LC] Aggregators, unattributed press. Built from open sources only; the field layer (◆) is withheld.

Built from open sources only. Nodes marked ◆ need field (HUMINT) validation; that layer is withheld.